The Nigerian intercity bus market is usually described as intensely competitive. On the routes most people travel, that is true. Across the network as a whole, it is not remotely true, and the gap between those two statements is the most under-examined fact in the sector.
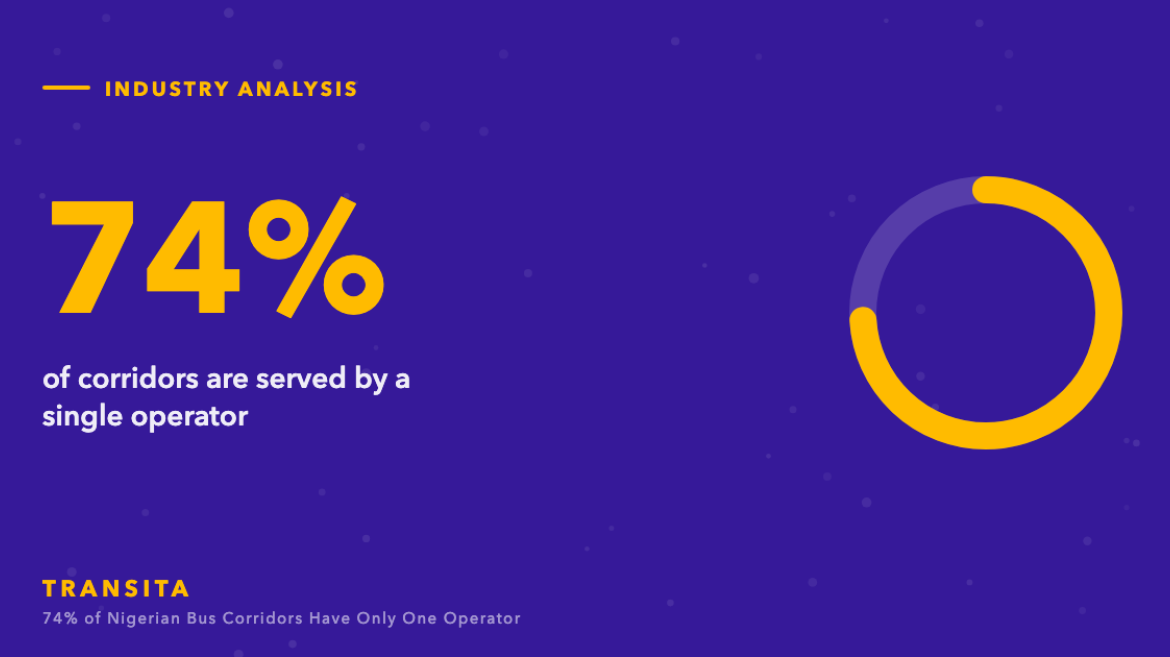
Of 208 city-pair corridors carrying live scheduled fares on the Transita index, 153 — 74% — have exactly one operator posting a price. Only 12 corridors have four or more carriers competing.
Key takeaways
- 153 of 208 corridors (74%) are single-operator.
- Only 12 corridors carry four or more operators.
- On contested corridors the fare floor varies by a median of 52% between carriers — a discount that simply does not exist on monopoly routes.
- Concentration is worst on the regional links, not the trunk routes.
Where the monopolies are
The single-operator corridors are not randomly distributed. They are overwhelmingly the regional and secondary links — the routes into smaller state capitals and market towns, and the lateral connections between cities that do not involve Lagos or Abuja. The trunk routes are contested; everything else largely is not.
| Operator | Corridors where it is the only carrier |
|---|---|
| Peace Mass Transit | 61 |
| GUO Transport | 55 |
| ABC Transport | 17 |
| GIGM | 14 |
| Efex Transport | 4 |
| Libra Motors | 2 |
The pattern follows network shape directly. Peace Mass Transit, with the largest terminal footprint on the index, is the sole operator on more corridors than anyone else — not because it has excluded competitors, but because it went to towns nobody else timetabled. That is a real service to those towns. It is also, unavoidably, market power.
What competition is actually worth
The value of a second operator on a corridor is measurable. On corridors with four or more carriers, the gap between the cheapest operator's fare floor and the most expensive operator's fare floor runs to a median of 52%. A passenger who compares captures that. A passenger on a monopoly corridor has nothing to compare and captures nothing.
The effect is not only on price. Single-operator corridors carry fewer daily departures, less schedule redundancy when a service is cancelled, and no competitive pressure on vehicle age or punctuality. The passenger experience on a thin route is worse in every dimension, and the fare is higher relative to distance.
Why this persists
Three structural reasons. First, terminal economics: a terminal in a small city has a fixed cost that only makes sense at a certain volume, and the second operator to arrive faces worse economics than the first. Second, route knowledge is not portable — local relationships, loading arrangements and agent networks take years to build. Third, and most fixable: demand on thin routes is invisible. An operator cannot see how many people searched for a Benin–Owerri service and did not find one.
The visibility argument
That third point is where an index changes something real. Aggregated search demand across operators is the only dataset that shows unserved routes before someone builds them. It is the same function a flight-search aggregator ends up performing for airlines: the search log is a route-planning input, not just a booking funnel.
This is the strongest argument for a shared booking layer in the sector, and it has nothing to do with convenience. A market with 74% single-operator corridors does not need better websites. It needs a mechanism for demand on thin routes to become legible to operators who could serve them. We develop this in the case for digitising bus ticketing.
Compare every operator on your corridor. Where there is competition, Transita shows you all of it.
Frequently asked questions
How competitive is the Nigerian bus market?
Highly competitive on trunk routes and barely competitive elsewhere. 74% of corridors on the Transita index have a single operator; only 12 have four or more.
Which Nigerian bus routes have the most operators?
Lagos to Aba and Lagos to Owerri each carry five operators, more than Lagos to Abuja.
Does comparing bus operators actually save money?
On contested corridors, yes — the median gap between the cheapest and most expensive carrier fare floor is around 52%. On single-operator corridors there is nothing to compare.